BKM data puts contactless at 81% in stores, who should manage a retailer’s payment setup?
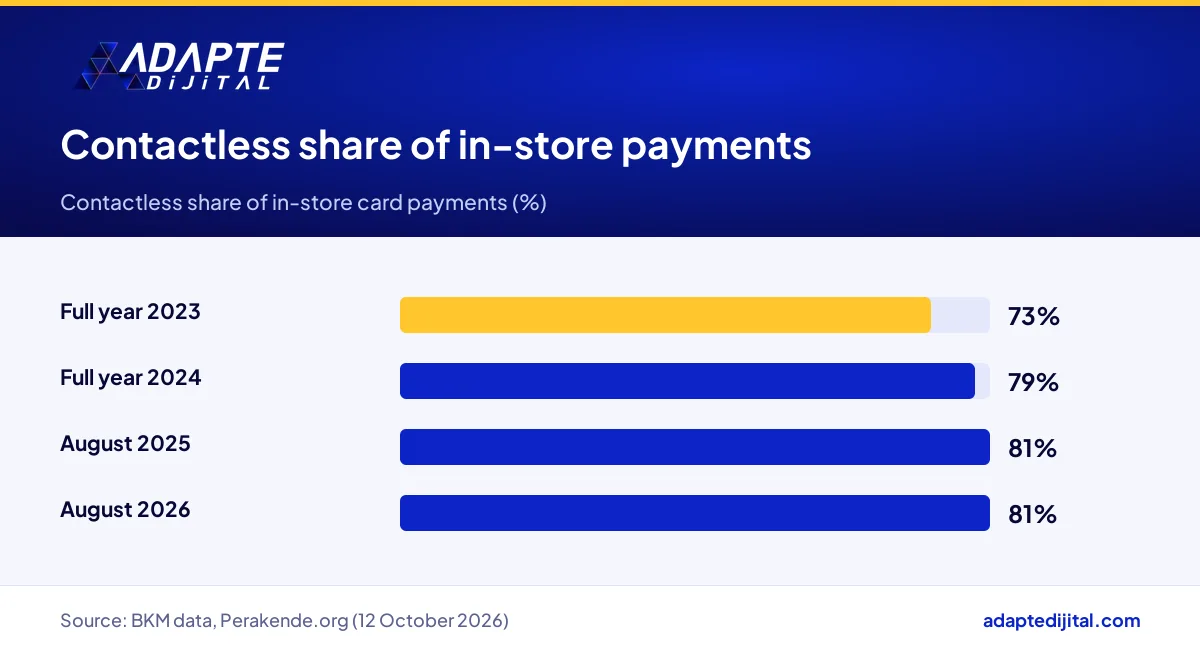
Contactless now accounts for 81% of in-store card payments in Türkiye, per data from BKM, the country’s Interbank Card Center, and that share held flat at 81% between August 2025 and August 2026 (Perakende.org, 12 October 2026). In the same column, Çağdaş Şen asks who should manage the POS terminals, fees and bank agreements behind a payment that never touches the counter.
Here is what it means for you: the checkout payment is no longer a habit, it is fixed infrastructure. The contactless share stands still while the money keeps growing; per BKM data, contactless payments reached TL 1,039.9 billion in August 2026, up 42% year on year. Whoever watches the fees taken from that volume has a direct hand on your store’s margin.
How has the contactless share of in-store payments moved in BKM data?
Per BKM data, contactless made up 73% of in-store card payments across 2023, 79% across 2024, and 81% in both August 2025 and August 2026. After a quick climb, the share has held at the same level for a year. What is growing is not the share but the value.
What does contactless payment change at a retailer’s checkout?
A contactless payment is one completed by holding a card or phone near the POS terminal, the card reader at the till. It shortens checkout time, shrinks the queue and keeps the card in the shopper’s hand. Small on their own, together they change how the till works.
Which businesses does the spread of contactless payment affect, and how?
The businesses most affected are those with frequent, low-value sales. Grocers, cafes, bakeries and pharmacies, whose tills stay busy all day, gain the most from speed and also feel the fee line the most.
Who should manage a store’s POS and fee agreements, and by which measure?
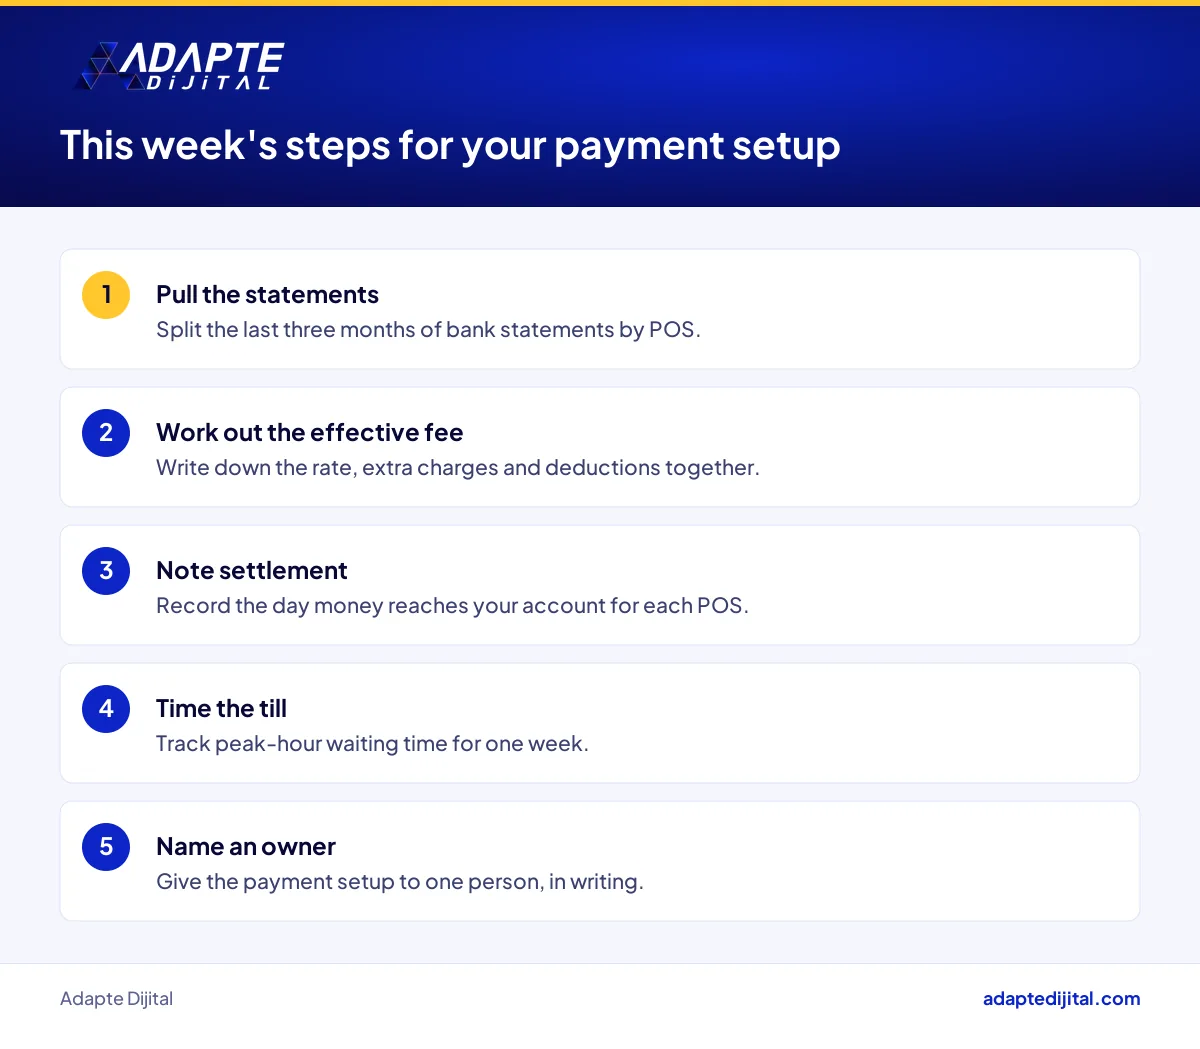
One person should own the payment setup, and that person should look at it through a financial lens, not a technical one. In a small business the owner or the accountant can take the role; in a chain, the finance team. The measure is not the number of devices but the effective fee, the settlement time and the monthly transaction volume.
How does the digital side of contactless payment connect with web, data and QR codes?
The payment in the store and the payment online are two faces of the same customer. In a BKM table, QR code payments reached 806.2 million transactions in January to August 2026, against 601.1 million in all of 2025. With more channels, keeping the data in one place matters more.
What should a store owner do about the payment setup this week?
Finish three jobs this week: pull the last three months of bank statements, work out the effective fee for each POS terminal, and name the person responsible for the payment setup in writing. You walk into your next bank meeting with a concrete table.
BKM’s monthly bulletins are a reliable starting point; the contactless figures appear in the BKM July 2026 press bulletin. On our retail page we keep following payments and checkout topics.
Quick Summary
- Per BKM data, contactless made up 81% of in-store card payments in both August 2025 and August 2026 (Perakende.org).
- Contactless payments reached TL 1,039.9 billion in August 2026, up 42% year on year (Foreks, BKM data).
- Online card payments that month came to TL 923.9 billion, 30% of total card value (Foreks, BKM data).
- The 83%, 86% and 91% scenarios for 2031 are Çağdaş Şen’s editorial outlook, not an official forecast.
- The payment setup should have one owner and be managed by effective fee and settlement time.
Short Glossary
- Contactless payment
- Contactless payment is the term used to describe a payment completed by holding a card or phone near a POS terminal.
- Effective fee
- Effective fee is the term used to describe the total cost a business actually pays on a card payment, including extra charges and deductions.
- Settlement time
- Settlement time is the term used to describe how long a card payment takes to reach the business’s bank account.
Frequently Asked Questions
Next Step
If you want to see your store, virtual POS and marketplace payment costs in one table, fill in the consult your expert form; our team will get back to you with first steps that fit your business.
Sources: Perakende.org, column by Çağdaş Şen, 12 October 2026 · Foreks, 17 September 2026 · BKM, mobile contactless and QR code payments table · BKM July 2026 press bulletin
Updated: October 2026
Sık Sorulan Sorular
Foreks, a Turkish financial news service quoting BKM data, reports 1,335.7 million contactless transactions in August 2026, up 9%. The 42% rise in value runs well ahead of that rise in count.
Total card payments in August 2026 came to TL 2,990.4 billion. Of that, TL 923.9 billion was paid online, which is 30% of the total value. Most card money in Türkiye still moves through physical stores, through the till.
No, they are not an official forecast. According to Çağdaş Şen, the contactless share in 2031 could reach 83% in a flat scenario, 86% in a base scenario and 91% with fast adoption. He calls these an editorial outlook, so do not read them as a projection by BKM or any other institution.
At lunchtime, when the queue reaches the door, shoppers turn around and leave. When payment takes seconds, the same cashier serves more people. If the till is not turning over at peak hour, the problem is often not the staff but the number of steps the payment takes.
Çağdaş Şen writes that treating the physical POS “only as a hardware investment is an incomplete approach.” Behind the device sit a bank agreement, a fee rate and settlement time, meaning how long the money takes to reach your account. A store’s real cost hides not in the device price but in the sum of those three.
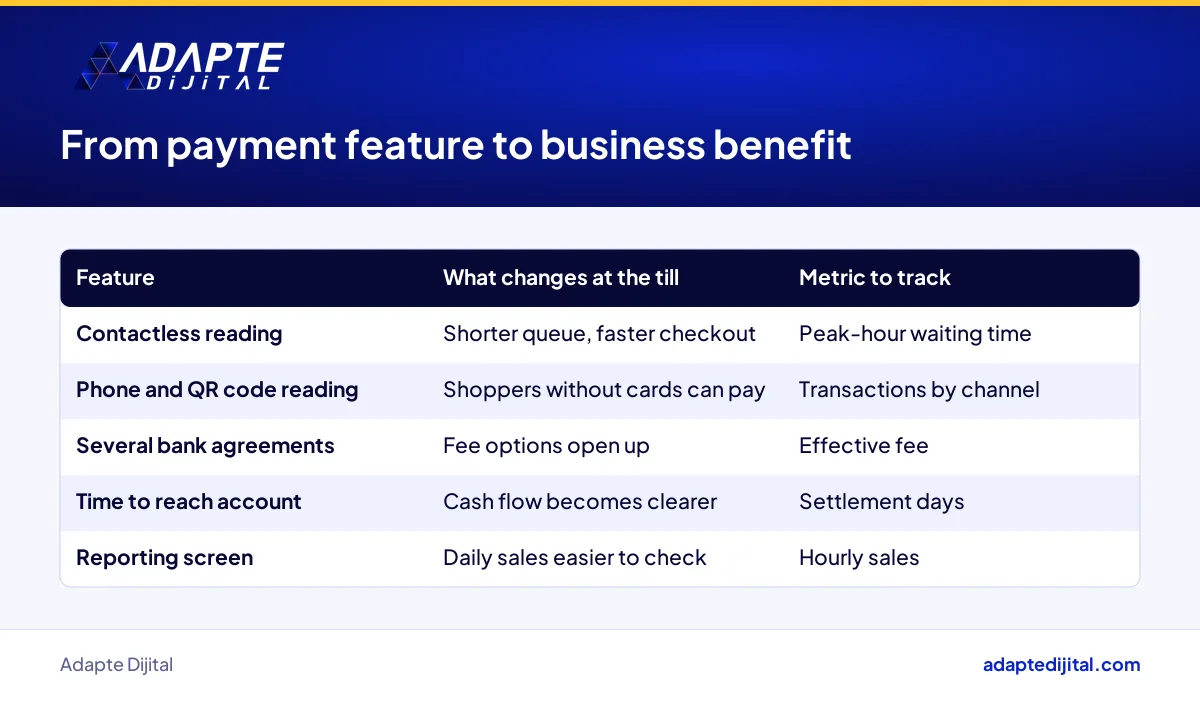
The desk suggests tying every payment feature to a checkout outcome. Contactless reading affects time at the till, support for several banks opens fee options, and a reporting screen makes daily sales easier to check. A benefit you cannot measure is one you cannot negotiate.
In a cafe the morning queue gets shorter, and the transaction count stays high even when the average basket is small. A business adding new items to its menu, such as cafes bringing ready-made liquid sauces onto the menu, wants every new line to pass through the till quickly. The struggle is that many small transactions add up to a large fee total.
For low-priced items like organic snacks placed at the checkout, payment has to finish in seconds. In chains, several banks and POS providers can run side by side, so comparing fees gets more complicated.
Accounting and finance teams feel it indirectly. As payment value grows, reading bank statements, picking out fees and tracking settlement takes more work.
The gap between the rate in the contract and the money that lands in your bank account gives you the effective fee. Extra charges and settlement timing can widen that gap. A rate can look low on paper and still be eaten away by deductions before the money reaches you.
In Çağdaş Şen’s hypothetical example, a 10 basis point improvement in the effective fee on TL 10 billion of annual card volume makes a TL 10 million difference a year. It is not data from a real retailer, only a worked example of how a small gap grows at scale.
The desk suggests looking again at least once a year, and whenever transaction volume changes noticeably. This is not legal or financial advice; verify the terms in writing with your bank.
The same BKM table shows 51.1 million mobile contactless transactions, meaning phone payments, in January to August 2026. Cards still dominate at the till, but a POS terminal that also reads phones and QR codes is now a basic requirement.
Hourly till sales show which hours and products deserve your ad budget. Put website orders next to store data and you see what sells on the shelf and what sells on the screen.
Store POS fees, virtual POS fees for online checkout and marketplace commissions should sit in one table. Seeing each channel’s payment cost makes it easier to decide where to steer sales.
For each POS terminal, write down the monthly transaction value, the total fee charged, any extra charges and the day the money reached your account. These four items show the gap between the contract rate and the real cost.
Note the waiting time at the till during peak hours for one week. Test contactless, phone and QR code reading on each device, one by one. A faulty or slow terminal loses money as quietly as stock gathering dust on a shelf.
Add virtual POS and marketplace deductions next to the store POS table. Seeing payment cost by channel is the first step to setting up e-commerce properly; through our e-commerce consulting work, we build this table together with businesses.
Per BKM data, no; the contactless share of in-store card payments held flat at 81% between August 2025 and August 2026. What is rising is payment value.
Yes, any business that works out its effective fee from recent statements can reopen the terms with its bank. This is not financial advice; confirm the terms with your bank in writing.
Name one person in charge; in a small business the owner or accountant, in a chain the finance team, can take on the role.