M&S adds 3 interest-free Klarna instalments online, should your web shop offer the same?
Marks & Spencer (M&S) now lets shoppers split their purchase into three equal, interest-free instalments through Klarna on M&S.com and the M&S app (Retail Technology Innovation Hub, 15 October 2026). The option covers fashion, home and beauty; the reports do not mention physical stores.
What it means for you: a large retailer is testing a payment option in its online basket first. Anyone running a web shop faces the same question: how does an instalment or pay-later option at checkout change conversion and basket size, and who carries its cost?
How does the Klarna payment option at M&S work?
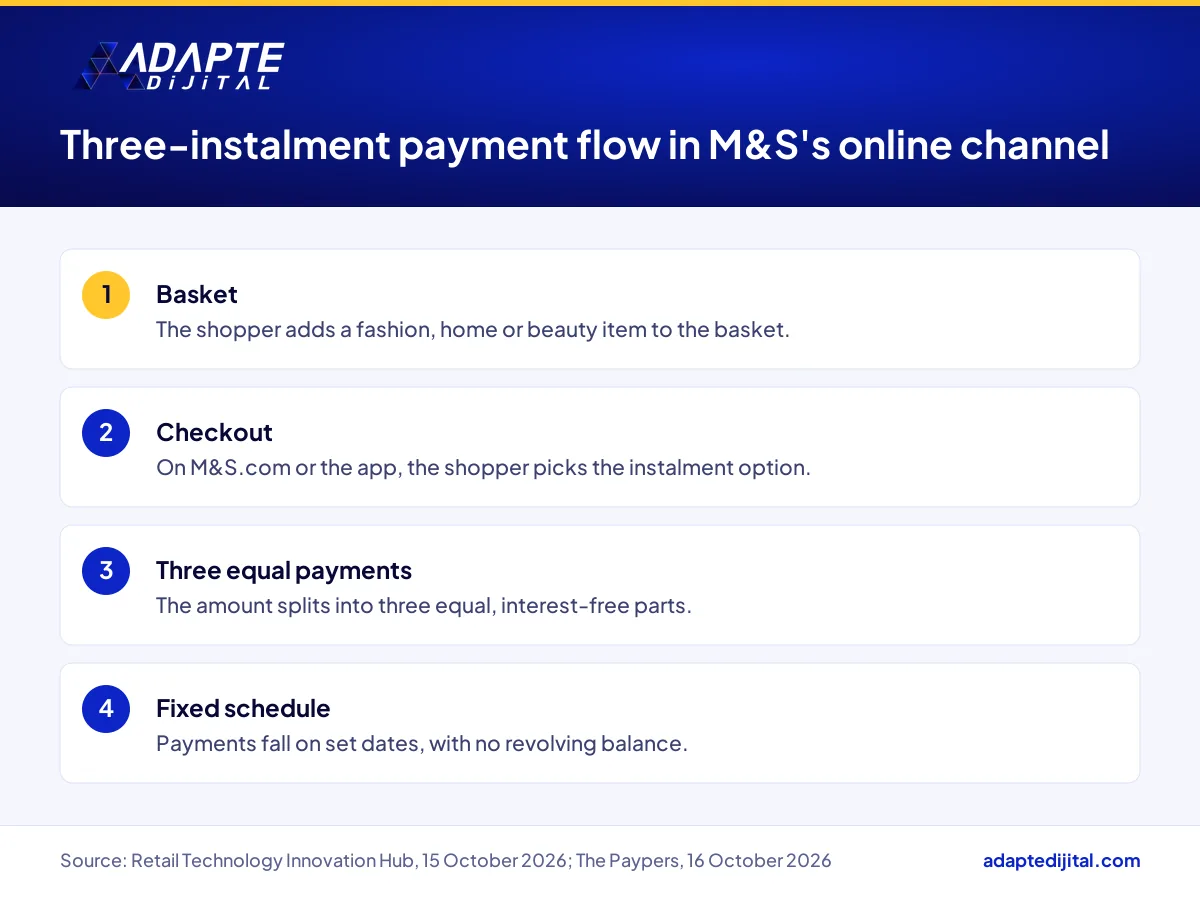
At checkout in M&S’s online channel, the shopper chooses to split the amount into three equal instalments. According to Klarna’s announcement, the instalments are interest-free, the schedule is fixed and there is no revolving balance (The Paypers, 16 October 2026). In plain terms, the shopper does not roll debt into next month and watch it grow; they make three payments known from the start.
How can an instalment option like M&S’s change sales in a web shop?
In two ways: it can keep a shopper who is about to give up at checkout, and it can encourage a bigger basket. A shopper adds an item, sees the total and closes the tab; an instalment option softens that moment. How big the effect is depends on your prices and your customers, so measure it with your own data.
Who carries the cost of an instalment option like Klarna’s at M&S?
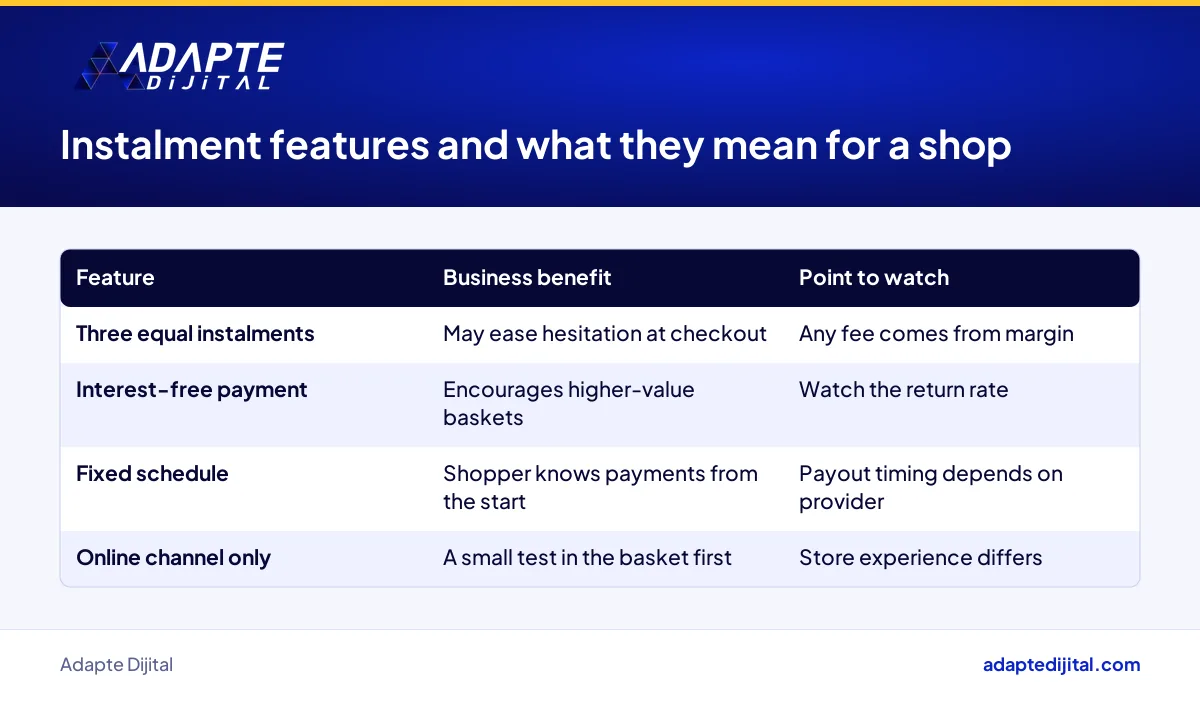
With interest-free instalments, the shopper pays no interest, so the cost has to sit somewhere else in the deal. The reports give no figure for what M&S pays and no fee structure. Ask your own payment provider in writing who carries the cost, and build the calculation on your own margin.
Who does M&S’s payment decision affect, and how?
Web shops selling fashion, home textiles and cosmetics feel it most directly, as shoppers get used to seeing such options at big brands. The likely winners are shops with high baskets and frequent repeat purchases. Small sellers with thin margins who cannot absorb a fee face pressure, and payment infrastructure providers and marketplaces feel the effect indirectly.
How should a web shop show an M&S-style instalment option online?
With the instalment amount on the product page, and the same wording in the basket and at checkout. If shoppers first see the option at the payment step, it cannot influence the add-to-basket decision. You can carry the message into ads and email, but the conditions must be as clear there as on the page.
What should a web shop owner considering instalments do this week?
BU BÖLÜMÜN ÖZETİ
- Ask your provider for a written offer
- Start with a small test
- Build the payment decision into the site experience
Split the last three months of basket abandonment data by checkout step, and list your highest-value product groups. Our desk recommends making the instalment decision with these two data sets plus a written offer from your payment provider. Ask your provider directly which instalment and pay-later options are available on your own payment infrastructure.
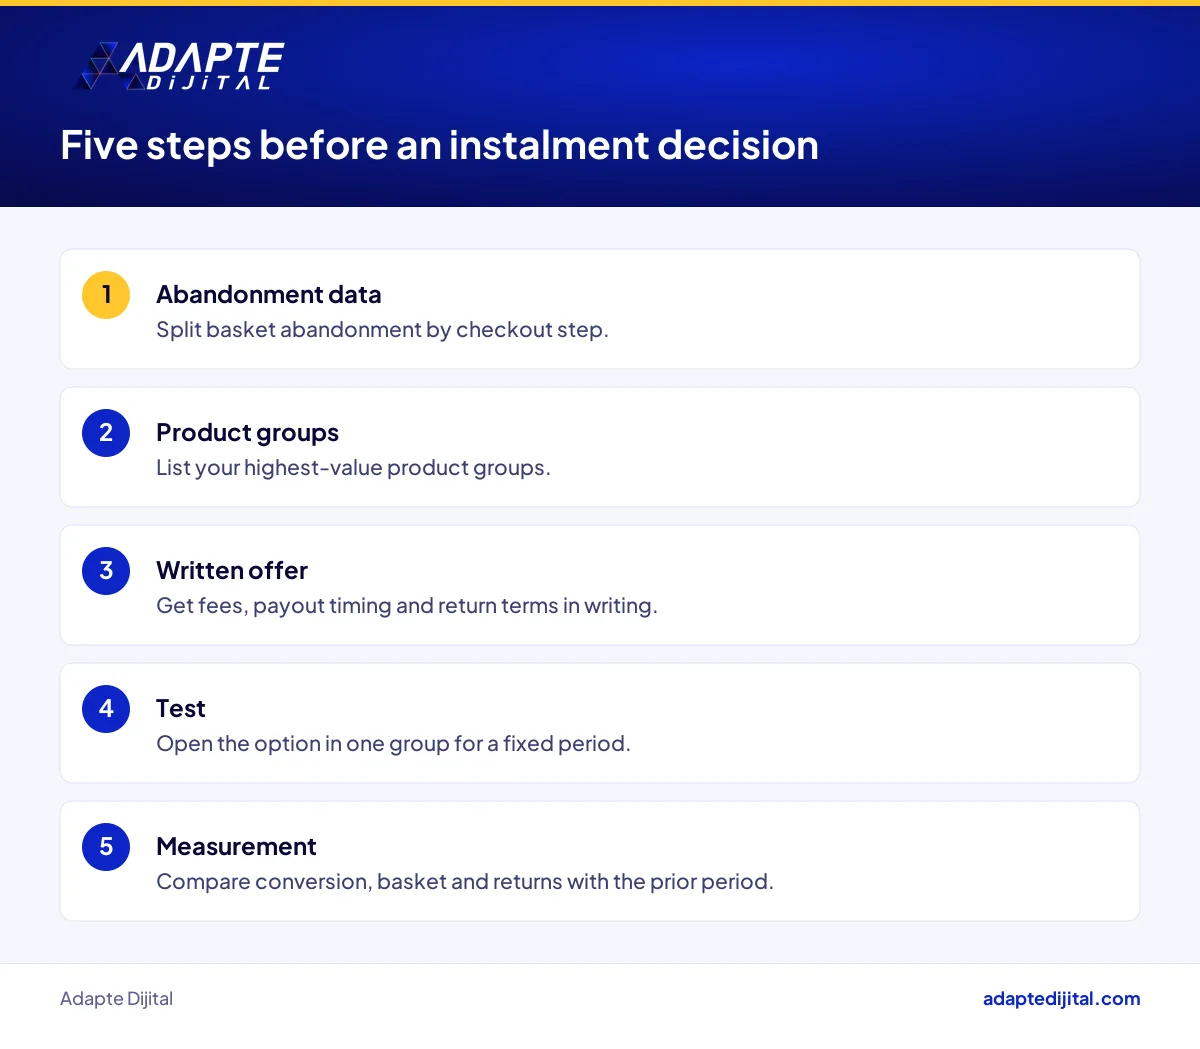
Ask your provider for a written offer
Fees, payout timing, return handling and contract length should sit in one document. A payment decision made on verbal information causes trouble at the first wave of returns.
Start with a small test
Open the option for one product group and a fixed period. Compare results with the previous period, then expand.
Build the payment decision into the site experience
Designing payment options together with the basket flow and a measurement plan is one of the jobs we handle in e-commerce consulting.
Quick Summary
- M&S offers three equal, interest-free Klarna instalments on M&S.com and its app (Retail Technology Innovation Hub, 15 October 2026).
- According to Klarna, the schedule is fixed and there is no revolving balance (The Paypers, 16 October 2026).
- The option covers fashion, home and beauty; the reports do not mention physical stores.
- According to Klarna, it works with more than 1.2 million businesses worldwide (The Paypers; Bisektor).
- Amount limits, late fees and credit check conditions do not appear in the sources.
Short Glossary
- Buy now, pay later
- Buy now, pay later is the payment model used to let a shopper take an item now and pay later or in instalments.
- Revolving balance
- Revolving balance is the credit term used to describe unpaid debt that rolls into the next period and can grow.
- Basket abandonment
- Basket abandonment is the e-commerce term used to describe a shopper leaving the site after adding items but before paying.
Frequently Asked Questions
Next Step
If you want to weigh your site’s payment options with your own basket data, fill in our consult your expert form.
Sources: Retail Technology Innovation Hub, 15 October 2026 · The Paypers, 16 October 2026 · Bisektor, 19 October 2026
Updated: October 2026
Sık Sorulan Sorular
Only digital ones: M&S.com and the M&S app. The sources do not mention physical stores. They also do not say which day the option went live; only the publication dates are known.
Fashion, home and beauty. These are categories where a basket can grow quickly and a shopper may hesitate at the payment step. The sources give no minimum or maximum amount for the instalments.
According to Klarna, it works with more than 1.2 million businesses worldwide (The Paypers; Bisektor). That is a company statement. The reports do not describe conditions such as late fees or credit checks.
It can, when price is the barrier. If baskets are abandoned because of shipping fees or delivery times, instalments change nothing, and the product just sits in the basket. First you need to know at which step, and why, baskets are left behind.
The shopper looks at the instalment instead of the total. An amount split into three makes adding a second item easier. If that also pushes up returns, the gain stays on paper.
In a shop with low prices and small baskets. Splitting a small basket into three gives the shopper little real relief; one more option on the payment screen just adds clutter.
The gross profit on the extra sales. If conversion rate and average basket value do not rise after you add instalments, any fee comes straight out of margin. Compare over at least a season, not a single month.
If an item bought in instalments comes back, what happens to the remaining instalments and any fee depends on the provider’s terms. Read those terms before you sign. Verify with the official source; this is not legal or financial advice.
It can. Ask whether the provider pays you the full amount up front or on a schedule. For a small business, that one answer makes a big difference at the till.
Consider offering instalments only on high-value product groups, not across the whole catalogue. That way you pay for the option only where it makes a difference. Make that choice with margin data at SKU level, the stock-keeping unit of each product.
You can test a payment option channel by channel. M&S offers it in the online basket first. According to Bisektor, Lululemon gives Klarna access by QR code in its UK and Germany stores; we look at how payment experience splits between store and online through MediaMarkt’s Ankara Podium store.
Payment companies are trying to carry spending into new categories. We cover a meal card company’s plan to move into travel in our piece on MetropolCard and Bilet.com.
When shoppers see “three equal payments” next to the price, they decide earlier. Place this line on the product card, right below the price.
The share of orders using instalments, their average basket value, checkout abandonment and return rate. Compare all four with the period before the option went live. In your analytics set-up, track payment method as a separate dimension.
According to the sources, the option is offered only on M&S.com and the M&S app. Physical stores are not mentioned.
It is worth testing if your baskets are high-value and abandonment clusters at the payment step. Decide by comparing the provider’s cost with the gross profit on the extra sales.
What happens to remaining instalments and fees on a returned item depends on the provider’s terms. Get those terms in writing from your provider before you sign.