Howden Türkiye appoints Burcu Nasuhoğlu to risk advisory, which risks should firms manage?
Howden Türkiye has appointed Burcu Nasuhoğlu as Senior Risk Advisory Director to develop the risk advisory and insurance broking services it offers to institutions and support its growth targets (ForInvest Haber, 8 October 2026; Perakende.org, 9 October 2026). Nasuhoğlu brings more than 26 years in banking and risk management. Her career started in banking in 1999, and from 2011 to 2025 she was Head of the Non-Financial Risks Unit.
Here’s what it means for you: an insurance broker is no longer positioning itself only as the middleman for a policy. It wants to be the adviser who maps what could go wrong in your business before it happens. And here’s something most people don’t know: banks run “non-financial risk” as a separate discipline, the work that deals with process, systems and reputation accidents rather than interest rates or currency swings. Its move to a broker’s desk shows the risk conversation widening for businesses in Türkiye in autumn 2026.
What role has Howden Türkiye given Burcu Nasuhoğlu?
Howden Türkiye has named Burcu Nasuhoğlu Senior Risk Advisory Director. According to the news, the goal of the role is to develop the risk advisory and insurance broking services offered to institutions. Nasuhoğlu is an economics graduate of Bilkent University and comes from a banking career that began in 1999. Her start date and former bank are not given.
What does an insurance broker’s risk advisory give a business?
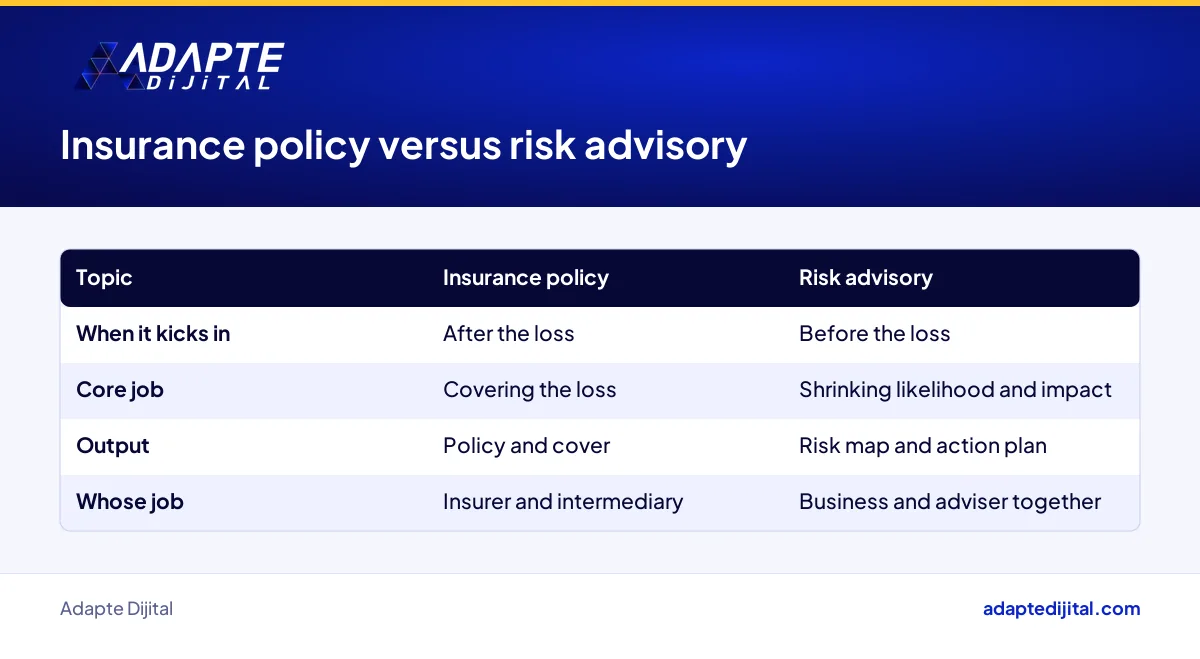
Risk advisory works before the loss, not after it. A policy is the contract that pays when an accident happens; risk advisory tries to shrink the chance of the accident and the damage it does. The policy is your umbrella; the risk adviser is the neighbour who checks the forecast and tells you which day to hang out the washing.
How do operational, reputational and climate risks affect a small business?
All three hit a small business faster than a large one, because there is little spare capacity. A day of system failure hits turnover, one wave of bad reviews hits footfall, and a flood or a long heatwave hits stock.
Who does Howden Türkiye’s risk advisory appointment affect, and how?
The direct effect lands on Howden Türkiye’s institutional clients, especially financial institutions. The group executive who comments on the appointment carries the title Head of Financial Institutions Risk Advisory. The indirect effect reaches businesses that sell goods and services to those institutions, because a large buyer tends to carry its risk questions down the supply chain.
What do information systems and reputational risk mean for a business’s digital side?
On the digital side, information systems risk means your website, payment infrastructure and customer data becoming unreachable for a day. Reputational risk shows up in search results, on your map listing and in marketplace reviews. Your digital shop window deserves its own row on the risk map.
What should a business owner do this week in light of Howden Türkiye’s risk advisory move?
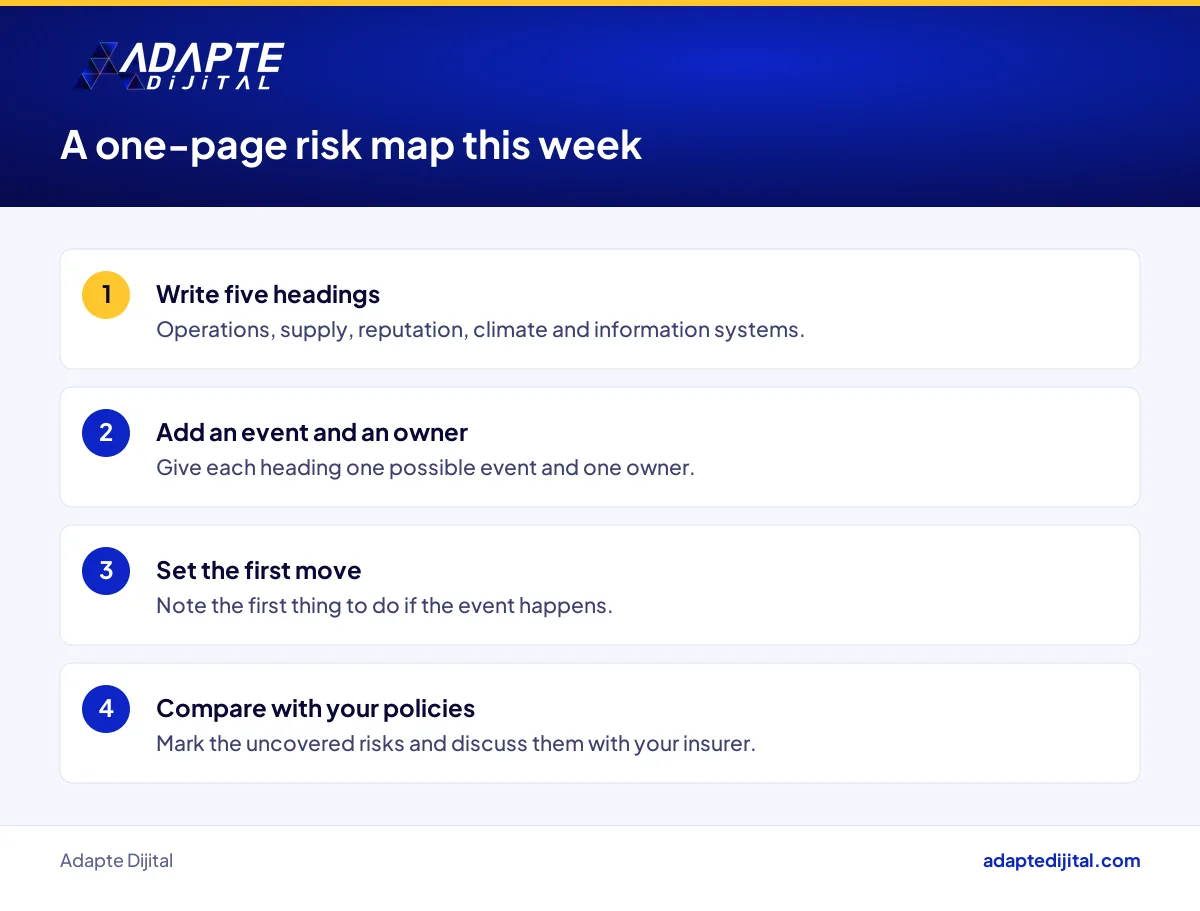
This week, draw up a one-page risk map. Write five headings: operations, supply, reputation, climate and information systems. Under each, add one possible event, one owner and one first move. Then lay it next to your policies and mark the gaps.
Quick Summary
- Howden Türkiye appointed Burcu Nasuhoğlu as Senior Risk Advisory Director (Perakende.org, 9 October 2026).
- Nasuhoğlu has more than 26 years of experience in banking and risk management (Perakende.org).
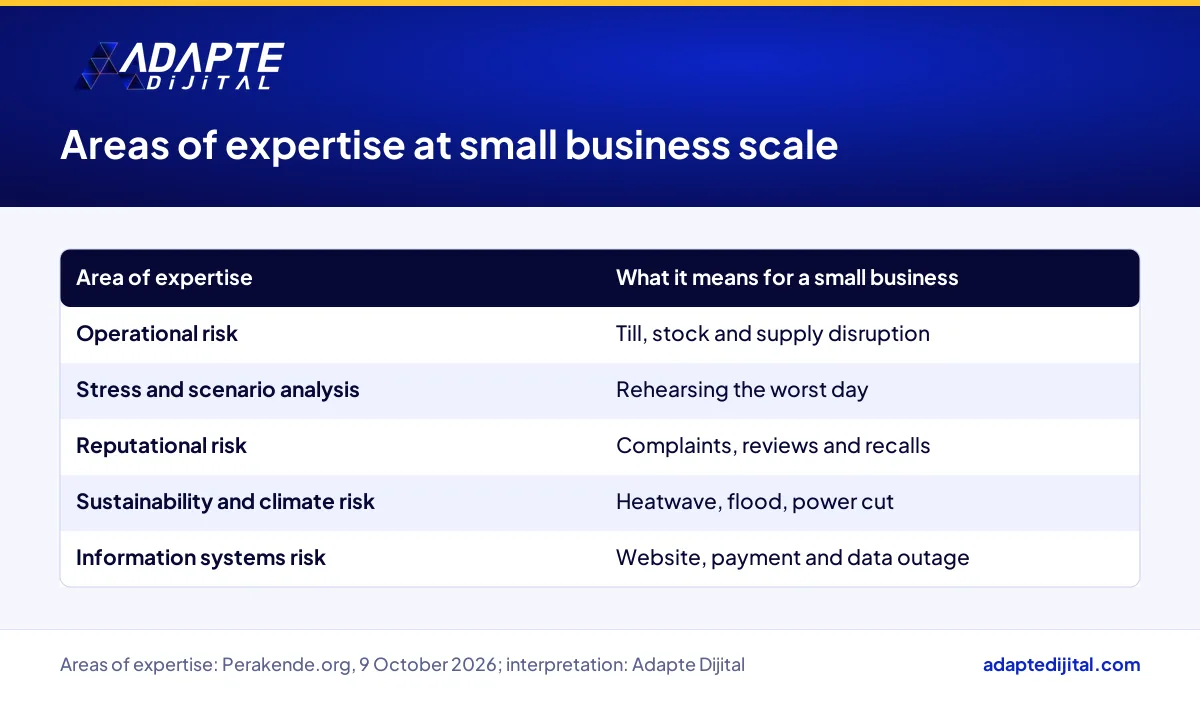
- Her expertise covers operational risk, reputational risk, climate risk and information systems risk.
- The service in the news is aimed at institutions; no change for SMEs has been announced.
- For a small business, the first step is a one-page risk map laid next to its policies.
Short Glossary
- Risk advisory
- Risk advisory is the service used to identify the losses a business could face in advance and plan ways to reduce them.
- Insurance broker
- An insurance broker is the intermediary used to search the market for a policy and negotiate it on behalf of the insured.
- Operational risk
- Operational risk is the term used for losses caused by failures in processes, people, systems or external events.
Frequently Asked Questions
Next Step
If you would like to map your business’s digital risks together, fill in the consult your expert form and we will get back to you.
Sources: Perakende.org, 9 October 2026 · ForInvest Haber, 8 October 2026 · Howden Türkiye corporate news page
Updated: October 2026
Sık Sorulan Sorular
The list reported by Perakende.org is long and technical: operational risk frameworks and capital models, stress and scenario analysis, reputational risk, sustainability and climate risk, and information systems risk. A stress test is the worked-out version of one question: if the worst day comes, what is left in the till? Scenario analysis asks it again with different stories.
Comments come from Atınç Yılmaz, CEO and Chairman of the Board of Howden Türkiye; Jonathan Humphries, Head of Financial Institutions Risk Advisory at Howden Group; and Nasuhoğlu herself. According to Nasuhoğlu, the risk agenda of institutions now stretches from operational risk to climate and sustainability risk. That is her assessment, not a measured finding.
According to the company’s own news page, Howden Türkiye opened its eighth branch, in Antalya, in 2025 and has more than 250 employees. Howden entered the Turkish insurance sector in 2011. The group was founded in London in 1994 and operates in 55 countries group-wide.
A broker searches the market for a policy on behalf of the insured and negotiates the terms. An agent sells the products of specific insurance companies. An advisory broker first maps the risks, then agrees with the owner which go to an insurer and which stay in-house.
The service in the news is aimed at institutions. The news does not say whether the appointment will bring any change in services for SMEs. The method itself, though, does not depend on size: a bakery chain with three branches can still ask which day the till will stop turning.
Operational risk is the trouble that comes from the work itself. A cashier’s mistake, a late supplier, spoiled stock, a crashed payment system: all sit here. For a small business, the first step is writing them down.
Reputational risk is what people say about your business turning into lost sales. A product recall, a complaint that spreads on social media or a campaign that gets misread sends customers walking out the door. You manage it with fast, consistent communication.
Yes, climate risk is real for a cafe too. In a heatwave the cooling load climbs, a sudden downpour floods the basement store, and a power cut empties the display counter. We cover the certification side of sustainability in our sister piece on Pluxee Türkiye’s ISO 14001 certification.
Ask three questions. What if your biggest supplier cannot deliver for two weeks? What if payments are down for a day, or the road outside is dug up? Write one owner and one first move next to each, and you have a stress rehearsal with no spreadsheet needed.
Banks and finance companies gain access to an adviser who knows the banking side from the inside. Howden Türkiye’s financial institutions page lists bank insurance, cyber risk and crime insurance.
Our reading: businesses that see risk only as a renewal date will struggle. A food producer or logistics firm supplying corporate clients may have nothing on paper when asked for a business continuity plan. When a big buyer asks those questions, “we have always worked this way” can cost you the tender.
Stores renting space in an AVM, the Turkish term for a shopping mall, franchise networks and multi-branch cafe chains feel it indirectly. Their tenant mix, lease and insurance terms are tied together.
Yes. An expired domain, a site with no backup or an admin password that only one person knows can stop sales overnight. List them on one page and put renewal dates in the calendar, so the site does not gather dust like stock nobody checks.
The reviews on your map listing are the doorstep of your digital store. New customers read unanswered complaints before deciding. Calm, regular replies are cheap insurance.
A loyalty programme, an email list and order history are all customer data. Where that data sits, who can reach it and what happens if it is lost should be written down. For legal obligations, verify with the official source; this is not legal or financial advice.
Write one line on what each policy covers next to the matching headings. A heading with nothing against it will either be managed in-house or discussed with your insurer. This is information, not insurance or financial advice; decide with a qualified professional.
We build this digital risk inventory with businesses as part of our digital consulting service. For the leadership decision on the operations side, see our piece on Ekici Peynir’s factory director appointment.
Now you know this: risk advisory comes before the policy, operational risk grows out of the work itself, and reputational and climate risks reach a small business faster than a big one. You can follow how similar appointments affect businesses on our retail page, where we interpret the Turkish retail agenda for you.
The news contains no such information. The stated goal is to develop the risk advisory and insurance broking services offered to institutions.
The method does not depend on size. A small business can start with a one-page risk map and talk it through with its insurer.
Perakende.org and ForInvest Haber do not name the bank. The news mentions a banking career that began in 1999 and the role of Head of the Non-Financial Risks Unit from 2011 to 2025.