How does KOSGEB Interest/Profit Share Support work for women and young entrepreneurs?
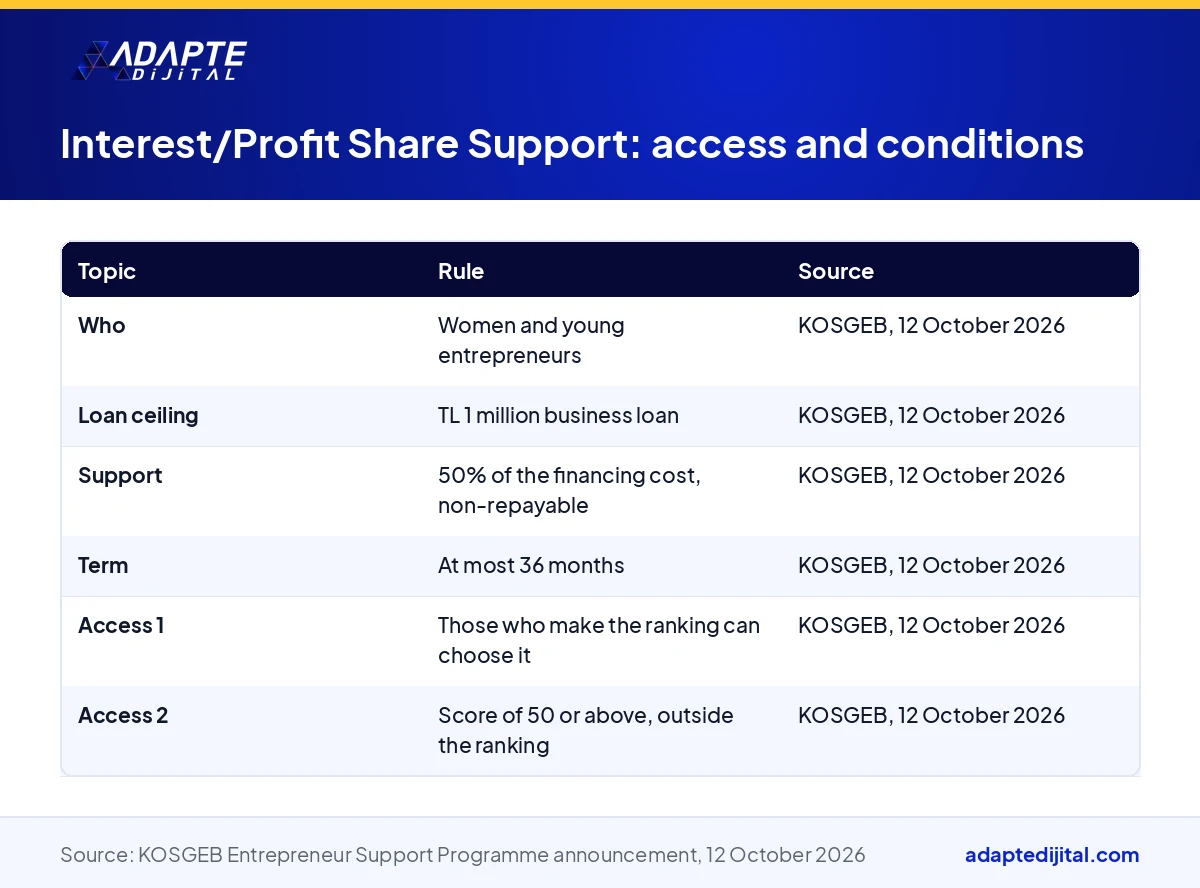
In the Entrepreneur Support Programme it renewed on 12 October 2026, KOSGEB announced Business Development Interest/Profit Share Support (Faiz/Kâr Payı Desteği) for women and young entrepreneurs: a business loan of up to TL 1 million, 50% of the financing cost non-repayable, and a term of at most 36 months (KOSGEB, 12 October 2026). There are two doors into the support: women and young entrepreneurs who make the Business Development ranking can choose it, and those who score 50 or above but miss the ranking also gain access. As of October 2026, when this article was updated, the Ministry of Industry and Technology had not published its digital company (dijital şirket) definition.
What this means for you: this support is not a grant but a model in which KOSGEB shares the cost of a loan. The bank gives the loan, and KOSGEB covers half of the interest or profit share. The business repays the principal and the other half within 36 months; the plan has to be built on that.
What is KOSGEB Interest/Profit Share Support, and what changed on 12 October 2026?
BU BÖLÜMÜN ÖZETİ
- A TL 1 million business loan: working capital, not investment
- 50% of the financing cost is non-repayable
- A term of at most 36 months
Interest/Profit Share Support is a separate door inside Business Development Support, opened to women and young entrepreneurs. The founder takes a business loan from a bank; KOSGEB covers half of the loan’s financing cost on a non-repayable basis. The ceiling is a TL 1 million loan, and the term is at most 36 months.
A TL 1 million business loan: working capital, not investment
The announcement says “business loan”. A business loan is the type of credit used to finance day-to-day operations. For large investment items such as buying machinery, there is the TL 2.25 million main item of Business Development Support.
50% of the financing cost is non-repayable
The financing cost is the interest on the loan or, at a participation bank, the profit share. KOSGEB covers half of this cost, and that half is not repaid. The principal and the other half of the cost belong to the business.
A term of at most 36 months
The loan term is at most 36 months. The monthly burden of a TL 1 million loan cannot be calculated without knowing the interest rate. In the plan, this burden should be written month by month alongside the revenue forecast.
Who gets access to Interest/Profit Share Support, and what is the 50-point rule?
BU BÖLÜMÜN ÖZETİ
- Women and young entrepreneurs who make the ranking: the right to choose
- A score of 50 or above: access even outside the ranking
- Collateral and the bank: cooperation with credit guarantee institutions
Access runs through the evaluation process of Business Development Support. The sector board scores the project. For women and young entrepreneurs this score produces two outcomes: the right to choose if they make the ranking, and the right of access through the 50-point threshold if they do not.
Women and young entrepreneurs who make the ranking: the right to choose
Women and young entrepreneurs who make the national top 500 or the top 3 in their province can choose Interest/Profit Share Support instead of the repayable main support. The main item may suit a large investment better, and the loan model may suit a cash need.
A score of 50 or above: access even outside the ranking
Women and young entrepreneurs with a board score of 50 or above gain access to this support even if they do not make the ranking. This rule opens a second door for a good project that lost the competition. How narrow the selection rate is, in numbers, is explained in our article on the selection rate in Business Development.
Collateral and the bank: cooperation with credit guarantee institutions
The announcement says there will be cooperation with credit guarantee institutions and financial institutions. Collateral is the hardest threshold for a new business to clear. The scope of the cooperation and which banks will take part have not been announced yet.
How does the TL 1 million loan and 50% support calculation work?
BU BÖLÜMÜN ÖZETİ
- Principal: up to TL 1 million, repaid in full
- Cost: interest or profit share, half from KOSGEB
- Term: cash flow within 36 months
The calculation has three items: principal, financing cost and term. The principal is entirely the business’s. Half of the cost comes from KOSGEB, half from the business. The term does not exceed three years.
Principal: up to TL 1 million, repaid in full
The support does not turn the loan into a grant. If TL 1 million is drawn, TL 1 million is repaid on the bank’s schedule. The founder’s gain is that half of the cost is covered by KOSGEB.
Cost: interest or profit share, half from KOSGEB
At a conventional bank you pay interest, at a participation bank a profit share; the support covers both. KOSGEB’s share is non-repayable. Whether the payment goes to the bank or to the business, and the implementation steps, are set in KOSGEB’s regulations; the announcement does not give this detail.
Term: cash flow within 36 months
The three-year term covers the business’s first three years. Which cost the loan will be spent on, and how its return will be measured, should be written in the plan. Spending that cannot be measured comes back as a burden on instalment day.
What is the difference between Performance Support and Interest/Profit Share Support?
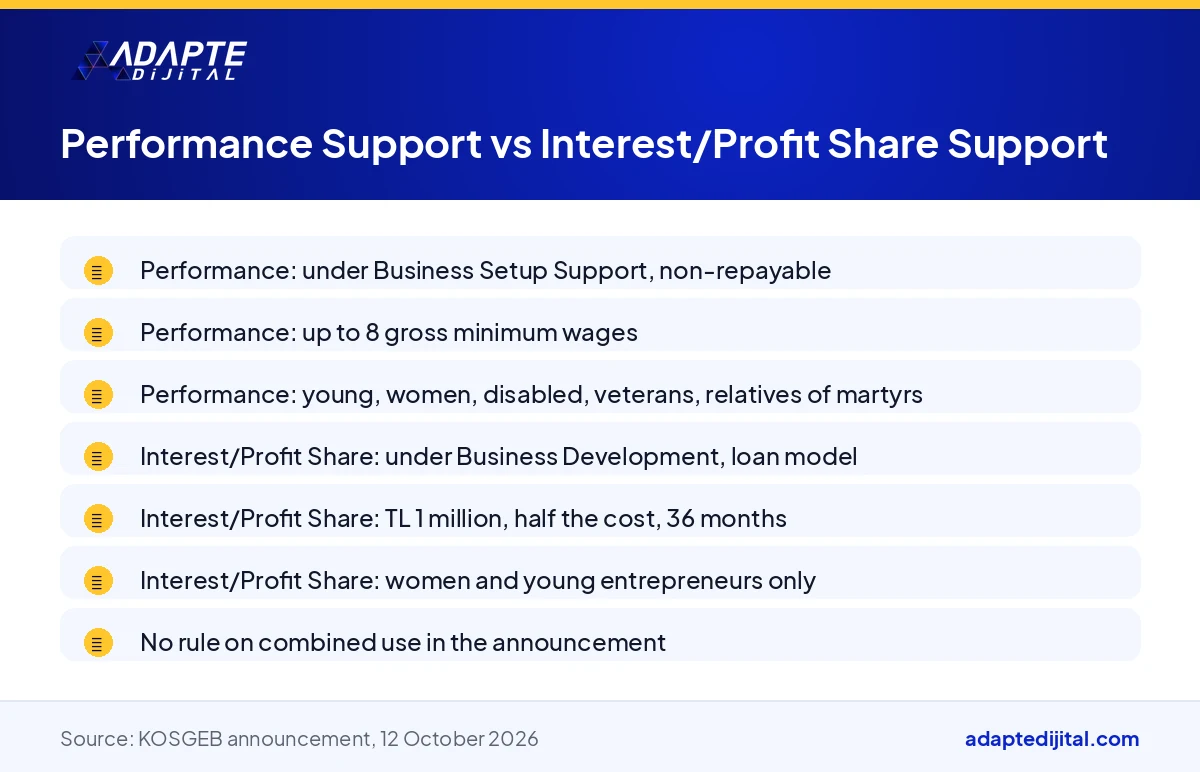
The new programme has two supports that mention women and young entrepreneurs. Performance Support sits inside Business Setup Support and is non-repayable; Interest/Profit Share Support sits inside Business Development and follows a loan model.
Performance Support: up to 8 gross minimum wages, a grant
Performance Support under Business Setup Support gives up to 8 gross minimum wages in non-repayable support to businesses whose founder is young, a woman, disabled, a veteran or a first-degree relative of a martyr. It is open to all KOSGEB-supported sectors, and applications are continuous.
Interest/Profit Share Support: a loan, half the cost, 36 months
Interest/Profit Share Support is open to women and young entrepreneurs; disabled founders, veterans and relatives of martyrs are not named in this item. The money comes from the bank, and KOSGEB shares the cost. The sector restriction is the Business Development list: manufacturing, telecommunications, programming, information services and scientific R&D.
Does Interest/Profit Share Support combine with the digital company?
Not today; there is no defined link between them. The only item KOSGEB has opened for digital companies is Platform Costs Support under Business Setup Support. Interest/Profit Share Support sits inside Business Development and does not require digital company status.
Platform Costs Support is in a separate programme
Platform Costs Support covers the platform registration fee of digital companies as defined by the Ministry; the amount has not been announced and the definition has not been published. This item sits in Business Setup Support. Who will receive it is explained in our article on KOSGEB platform registration fee support.
How do women and young entrepreneurs prepare for this support?
BU BÖLÜMÜN ÖZETİ
- A plan that targets the score: numbers for the 50 threshold
- A 36-month cash flow: instalment and revenue side by side
- Collateral and the bank meeting: start early
- Build the digital side together with incorporation
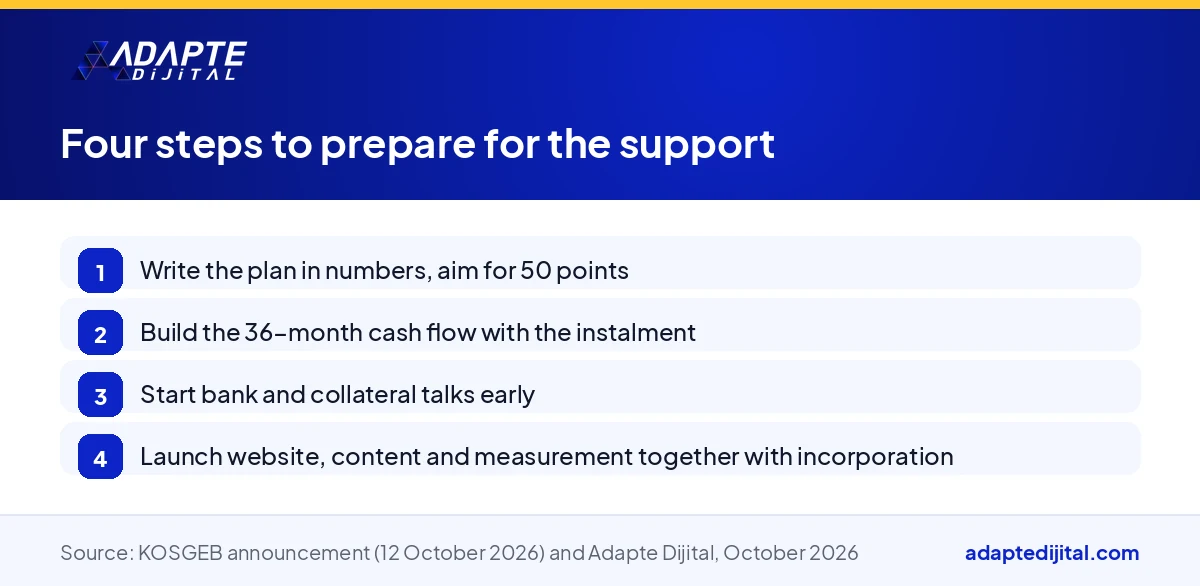
The centre of preparation is the sector board’s 50 points. What earns the score is a measurable plan: costs, revenue, timeline and numbers.
A plan that targets the score: numbers for the 50 threshold
The board looks at whether the project is written in numbers. Market, customers, costs and repayment should be described in numbers. The digital section speaks the same language: website, number of pages, number of AI-SEO-friendly articles, accounts and measurement. The plan’s digital timeline is in our article on the digital preparation timeline before KOSGEB support.
A 36-month cash flow: instalment and revenue side by side
The loan instalment is at the door every month for 36 months. The plan should state from which month revenue will cover the instalment. If the website and measurement are built early, the revenue forecast rests on Search Console and GA4 data.
Collateral and the bank meeting: start early
The details of cooperation with credit guarantee institutions have not been announced. Starting the bank meeting without waiting for the score result saves time.
Build the digital side together with incorporation
Domain name, an AI- and user-friendly website, content, accounts and measurement should start in the same month as incorporation. We run the planning of the digital side in our digital consulting service. We collect support developments on our digital company page.
Quick Summary
- Interest/Profit Share Support: a business loan of up to TL 1 million for women and young entrepreneurs (KOSGEB, 12 October 2026).
- 50% of the financing cost is non-repayable; the term is at most 36 months; the principal is the business’s.
- Access: those who make the Business Development ranking can choose it; those who score 50 or above but miss the ranking also gain access.
- Performance Support is different: under Business Setup, up to 8 gross minimum wages, non-repayable.
- No defined link to the digital company; the separate item for digital companies is Platform Costs Support, and the definition had not been published in October 2026.
Short Glossary
- Financing cost
- Financing cost is the term used for the interest or profit share paid on a loan.
- Business loan
- A business loan is the type of credit used to finance day-to-day operations and running costs.
- Credit guarantee institution
- A credit guarantee institution is an institution set up to act as guarantor for the loan of a business with insufficient collateral.
Frequently Asked Questions
Next Step
If you want to plan the digital side of your company together with incorporation, book a discovery call on our digital company page; we stay your friendly adviser throughout your digitalisation journey.
The definition and conditions of the digital company scheme are not final yet; support amounts and conditions may change. Check the latest information with the Ministry of Industry and Technology, KOSGEB and the Official Gazette before deciding. This is not legal or financial advice.
Sources: KOSGEB, Entrepreneur Support Programme renewed (12 October 2026) · Bigpara/DHA-AA, Ministry report and KOSGEB figures (7-8 September 2025) · Official Gazette, Issue No. 33270 (4 June 2026)
Updated: October 2026
Sık Sorulan Sorular
The announcement gives no rule on using the two supports together. One belongs to the setup-stage programme, the other to the growth-stage programme. Who benefits under which conditions is covered separately in our article on who can benefit from digital company status.
Whether KOSGEB will add a digital company condition to its Business Development items once the Ministry publishes the definition is unknown. The concept as a whole and the open questions are in our article what is a digital company.
The bank’s and KOSGEB’s rules decide which costs a business loan can be used for. Digital items such as website, content and measurement are listed under the software and service purchase headings of the main Business Development item. It cannot be claimed that the same acceptance applies to the loan; the answer to that question lies with KOSGEB.
A business loan of up to TL 1 million for women and young entrepreneurs; 50% of the financing cost is covered by KOSGEB on a non-repayable basis, and the term is at most 36 months. The principal and the remaining cost belong to the business.
Women and young entrepreneurs who make the Business Development ranking can choose it; women and young entrepreneurs who score 50 or above from the sector board but miss the ranking also gain access.
No. There is no such condition in the announcement; the only item aimed at digital companies is Platform Costs Support under Business Setup Support. The Ministry’s definition had not been published as of October 2026.