A digital company gets up to 3 years of chamber fee relief, are tax criteria set yet?
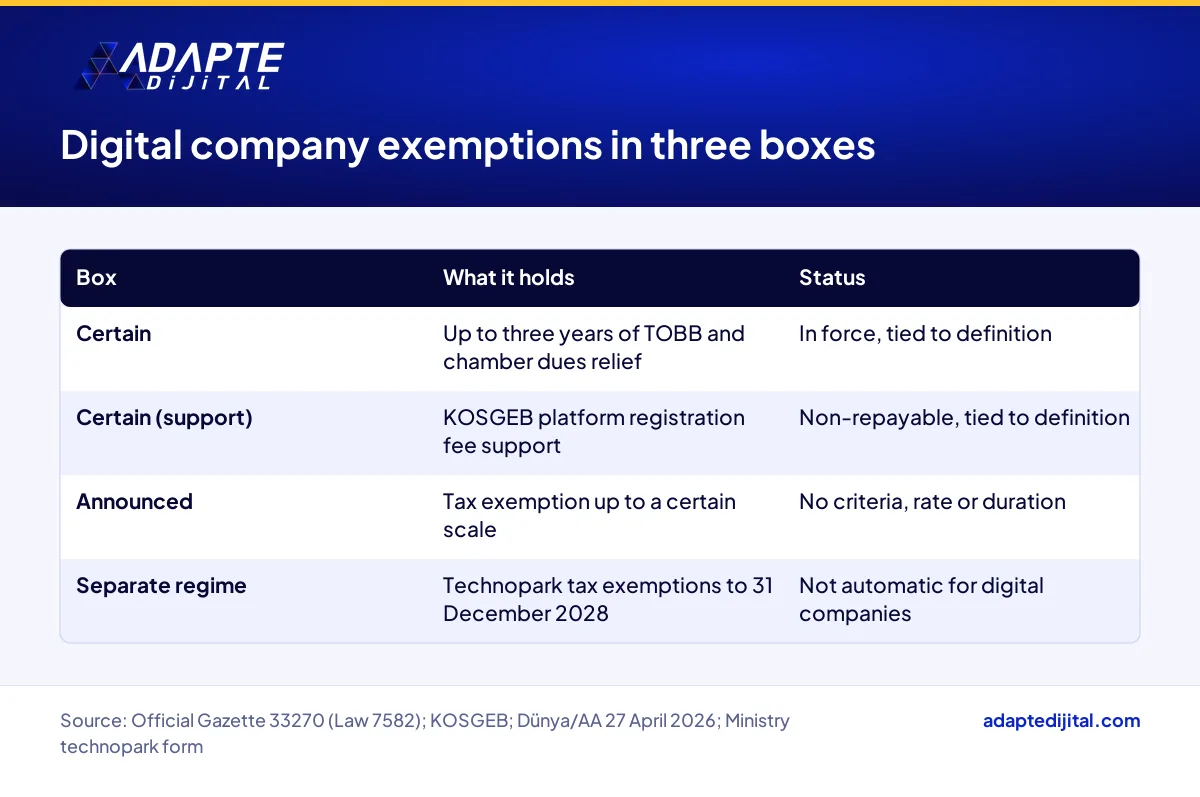
The only exemption written into law for a digital company (dijital şirket) today is relief from TOBB, chamber and exchange fees and dues for up to three years from incorporation, while a tax exemption has only been announced, with no criteria published (Law 7582, Official Gazette 33270, 4 June 2026). TOBB is the Union of Chambers and Commodity Exchanges of Türkiye. Even the dues relief depends on the Ministry of Industry and Technology’s digital company definition, which had not been published as of 14 October 2026. Technopark tax exemptions are a separate regime and do not apply to digital companies automatically.
What this means for you: in your cash plan today, only the dues relief can go in, and only if the definition comes out. Counting on a tax exemption now would be counting chickens before they hatch. Our digital company page covers the definition and setup questions separately.
Which exemption is certain for a digital company today?
The TOBB and chamber dues exemption. Article 11 of Law 7582 adds paragraph 16 to Article 3 of Law 5746. Under it, companies set up and run in line with the Ministry’s definition by founders who have qualified as incubation entrepreneurs under Law 4691 are exempt from the fees and dues in Article 24 of Law 5174 for up to three years from incorporation.
Will digital companies get a tax exemption, and what criteria were announced?
They might, but there are no criteria today. In his 27 April 2026 announcement, Minister Kacır said companies meeting certain criteria would be offered tax exemptions and cost incentives until they reach a certain scale. Which tax, the criteria, rate, duration and growth threshold were not announced, and no law or communiqué delivering the promise was found.
Do technopark tax exemptions apply to a digital company automatically?
No, they do not. Technopark exemptions are a separate regime based on Law 4691 and tied to activity “carried out in the zone”. Fitting the digital company definition does not bring a company into that regime. No provision granting technopark rights to digital companies was found.
Which founders do digital company exemptions affect, and how?
BU BÖLÜMÜN ÖZETİ
- Winner: the software company doing R&D in a technopark
- Under pressure: the founder who plans around a tax exemption
- Indirectly: chambers and venture capital
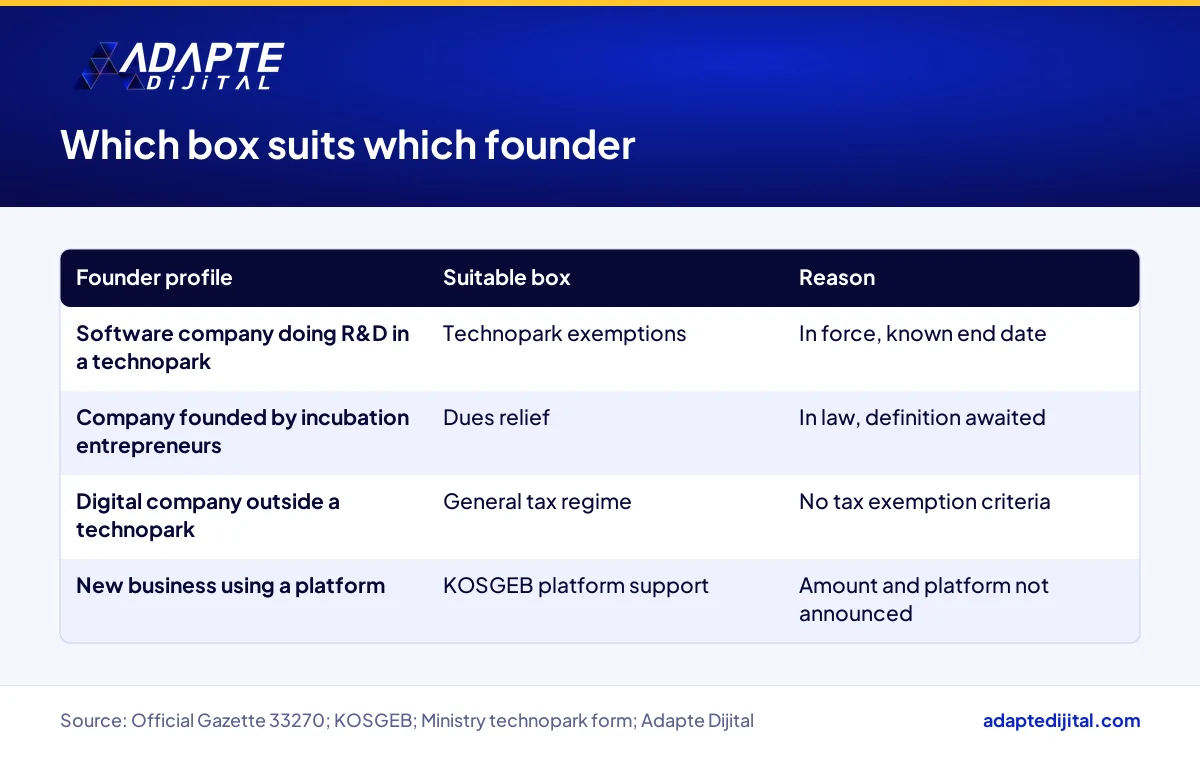
The effect depends on where a company is set up and by whom. Founders starting software, game or data companies in Istanbul, Ankara or Kocaeli in autumn 2026 land in different boxes. The comparison uses four criteria: certainty, scope, duration and who holds the right.
Winner: the software company doing R&D in a technopark
This company uses exemptions that are in force today, with known end dates and calculable effects. If its founder has qualified as an incubation entrepreneur and the definition fits, the dues relief may come on top. That is the reason it wins: certainty and measurability sit with the technopark regime.
Under pressure: the founder who plans around a tax exemption
A founder outside a technopark who writes a tax exemption into the budget rests the cash plan on a gap until criteria appear. If the margin is calculated on that assumption and the criteria come out narrow, the till stops ringing.
Indirectly: chambers and venture capital
Chambers and exchanges collect no fees or dues from an exempt company for up to three years. Under Law 7263, technopark taxpayers with exempt earnings above TL 1,000,000 channel 2% of them into venture capital or to incubation entrepreneurs.
What do digital company exemptions mean for software sales, platforms and the website?
It shows in three places: the software VAT exemption, which depends on a technopark; KOSGEB platform fee support, which depends on the definition; and exemption claims on a website, which need care today.
What should a founder considering a digital company do this week?
BU BÖLÜMÜN ÖZETİ
- Monday: build the cash plan without exemptions
- Wednesday: check the technopark and incubation option
- Friday: the checklist
Do three things this week: build the cash plan without exemptions, check the technopark and incubation entrepreneur option, and close the checklist. You can weigh which route suits you with the criteria in our article on whether to wait or incorporate now.
Monday: build the cash plan without exemptions
Put the tax exemption and platform support at zero, and the dues relief in as a scenario. Ask your accountant what the chamber dues would be for your company.
Wednesday: check the technopark and incubation option
If you develop R&D or software, ask the managing company about technopark entry conditions. Since the dues relief depends on incubation entrepreneur status, ask in the same meeting how that status is gained.
Friday: the checklist
The list: (1) cash plan without exemptions, (2) dues relief as a scenario, (3) technopark option assessed, (4) no exemption promise on the site or in decks, (5) sources to read once the definition is out. We build exemption scenarios into a digital investment plan through our digital consulting service.
Quick Summary
- What is certain in law is up to three years of TOBB, chamber and exchange fee and dues relief from incorporation (Official Gazette 33270, Law 7582).
- The dues relief entered into force on 4 June 2026, but applying it depends on the Ministry’s unpublished definition.
- A tax exemption was announced on 27 April 2026 with no criteria, rate or duration (Dünya/AA).
- Technopark exemptions run until 31 December 2028 and do not apply to digital companies automatically (Ministry information form).
- KOSGEB platform support is not a tax exemption but a non-repayable support tied to the definition.
Short Glossary
- Incubation entrepreneur
- Incubation entrepreneur is the status used to describe a founder who has gained this standing under Law 4691 on Technology Development Zones.
- Cancellation against withholding
- Cancellation against withholding is the incentive method used to write off income tax withheld from wages instead of paying it over.
- Dues exemption
- Dues exemption is the legal arrangement used to relieve a company of TOBB, chamber and exchange fees and dues for a set period.
Frequently Asked Questions
Next Step
If you would like to weigh exemption scenarios against your own business plan together, fill in the consult your expert form.
The definition and conditions of the digital company scheme are not final yet; check the latest information with the Ministry of Industry and Technology, KOSGEB and the Official Gazette before deciding. This is not legal or financial advice.
Support amounts and conditions can change; check the current terms on the institution’s official page before applying. This article is not financial or legal advice.
Sources: TÜRMOB circular, Law 7582 amending certain laws (Official Gazette, 4 June 2026) · Official Gazette 33270 · Dünya (AA) (27 April 2026) · Ministry of Industry and Technology, technopark incentives information form (28 August 2023) · KOSGEB Entrepreneur Support Programme
Updated: October 2026
Sık Sorulan Sorular
Yes, it entered into force on 4 June 2026. Applying it, however, depends on the Ministry’s definition, so no company type benefiting from it has been described yet. Why the definition matters so much is explained in our article what is a digital company in Türkiye.
That is not clear. The law says “up to three years”, and whether every company gets a full three years or the definition sets the period is open. Dues vary by chamber and capital, so no single TL figure applies.
No, it is a support payment. Under the Entrepreneur Support Programme of KOSGEB, Türkiye’s Small and Medium Enterprises Development Organization, a business fitting the definition receives Platform Costs Support equal to its platform registration fee, at 100% and non-repayable. It covers a cost item, not the tax burden, and it also depends on the definition.
The 2027-2029 Medium-Term Programme, announced on 10 September 2026, lists launching the Digital Company scheme among its targets. It mentions easier incorporation and an exemption at the start-up stage. This is an MTP target, not a tax provision in force.
Some commentary claims that a digital company is a new company type or that income tax rules have changed. These claims do not appear in any official text. What the official texts contain today is only the dues exemption in Law 5746.
According to the Ministry of Industry and Technology’s technopark information form, software, design and R&D earnings from work in the zone are exempt from income or corporate tax until 31 December 2028. Income tax on the wages of R&D, design and support staff is cancelled against withholding until the same date. Papers relating to the wages of R&D and design staff are exempt from stamp duty.
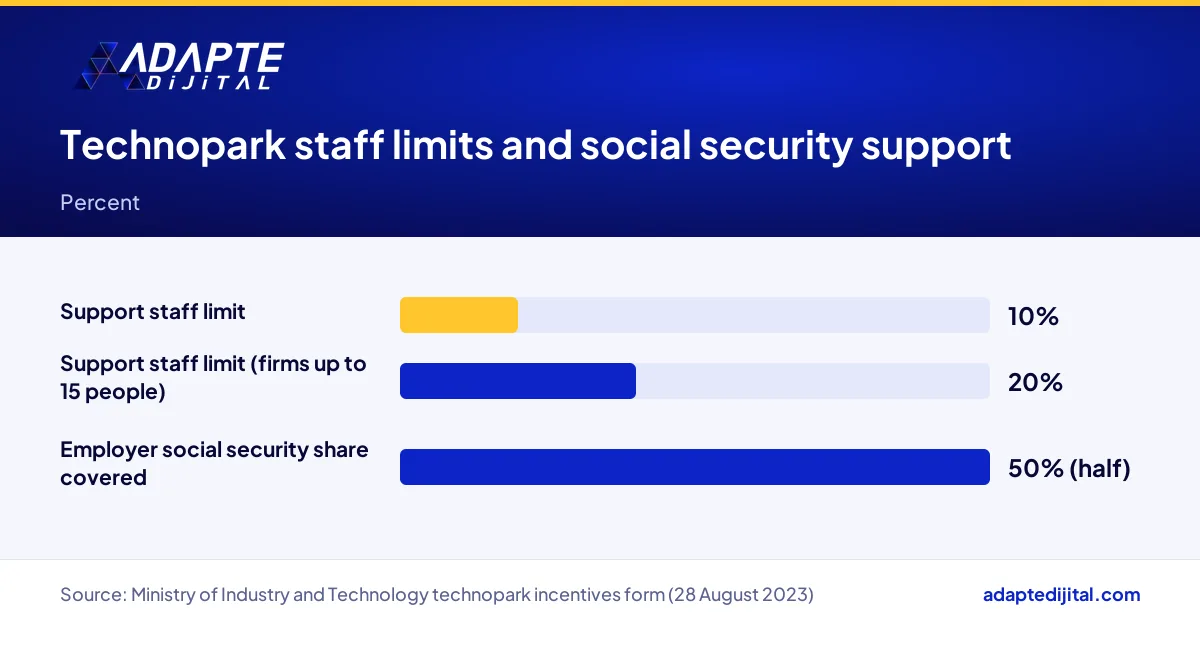
Support staff cannot exceed 10% of R&D and design staff, or 20% in firms with up to 15 people. Half of the employer’s social security share is covered for staff whose wages fall under the exemption. Listed software produced in the zone is exempt from VAT on delivery for as long as the earnings exemption lasts.
The form is dated 28 August 2023. Law 7263 extends the exemption period to 31 December 2028, but later changes were not checked against the current text. Check current rules with the managing company first.
Delivery of listed software produced in the zone, including system, data management, business application, internet, game and mobile software, is VAT-exempt. A digital company building the same app outside a technopark does not get this exemption automatically.
According to KOSGEB, a business fitting the definition receives non-repayable support equal to its platform registration fee. What the platform is and how much the fee will be have not been announced. Budget this item at zero for now.
A phrase like “tax-exempt digital company” on a site or in an ad is a promise with no official basis today. In investor decks and on the about page, mention only the provision in force.
No tax exemption specific to digital companies is in force today. One was announced on 27 April 2026, but its criteria, rate and duration have not been published.
The provision entered into force on 4 June 2026, but it depends on the Ministry’s digital company definition and the incubation entrepreneur condition. It does not look applicable before the definition is published.
Technopark exemptions are a separate regime tied to activity in the zone. No provision was found that grants them to digital companies automatically.